

Updated October 12, 2026
The residential appraisal industry is undergoing one of its most significant transformations in decades, and the changes will affect more than just the appearance of an appraisal report.
Beginning November 2, 2026, Fannie Mae and Freddie Mac are scheduled to require a new appraisal reporting standard known as Uniform Appraisal Dataset (UAD) 3.6, subject to temporary exceptions for approved lenders.
Along with the new reporting requirements, the mortgage industry is expanding its use of hybrid appraisals, desktop appraisals, standardized property data collection and alternative valuation processes.
There are also important changes to how appraisers document property condition, improvements, accessory dwelling units (ADUs), and a property’s highest and best use.
For homebuyers, sellers, Realtors and mortgage professionals, understanding these developments can help prevent confusion and make the transaction process smoother.
Here’s what’s changing and why it matters.
1. UAD 3.6: A Major Redesign of the Residential Appraisal
For years, residential appraisers have relied on familiar forms such as the 1004 for single-family residences, 1073 for condominiums and other forms for different property types.
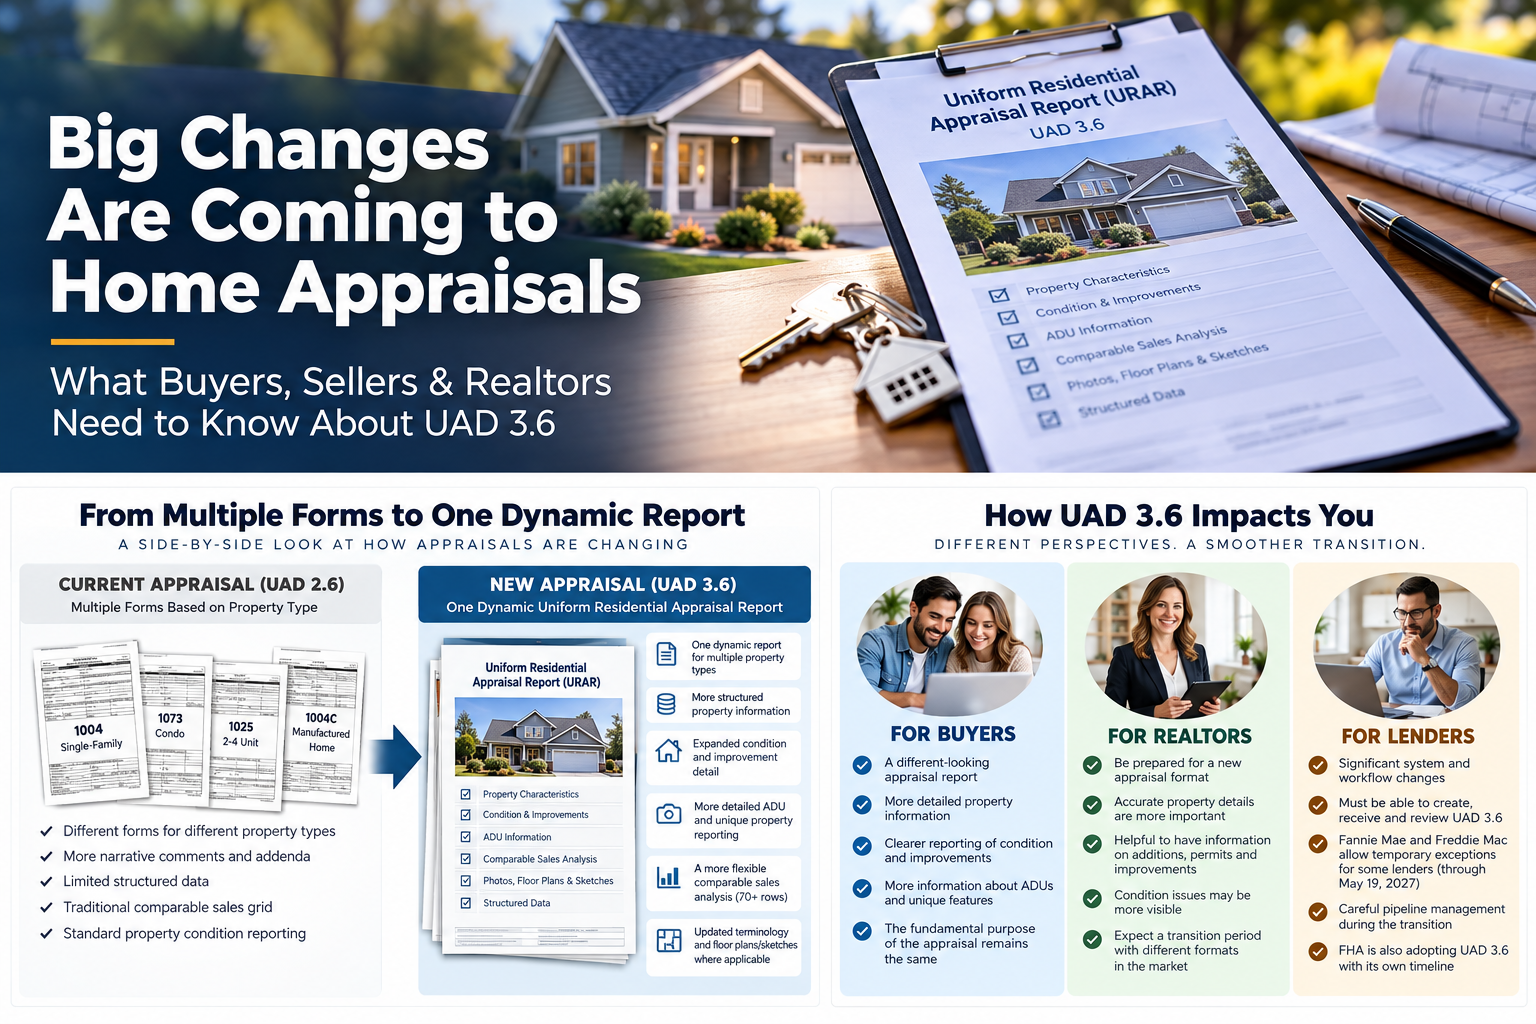
UAD 3.6 replaces those separate reporting formats with a new Uniform Residential Appraisal Report (URAR).
Rather than requiring appraisers to fit information into a fixed form, the URAR is a dynamic report that adapts to the property and appraisal assignment.
The new reporting system is designed to provide:
- More standardized property information
- More detailed reporting of property characteristics and improvements
- Expanded documentation of condition and deficiencies
- More structured reporting of accessory dwelling units
- Updated terminology for finished living areas
- More flexible comparable-sales analysis
- Improved data consistency for lender review
The fundamental purpose of an appraisal remains unchanged: to provide an independent, supported opinion of a property’s market value.
What changes is how that information is collected, organized, documented and communicated.
2. November 2, 2026: What Happens When the New Requirements Begin?
Fannie Mae and Freddie Mac have established November 2, 2026, as the mandatory transition date for new UAD 3.6 appraisal submissions.
However, on September 30, 2026, the agencies announced an important exception.
Lenders that need additional time to complete their implementation may request a temporary policy exception allowing them to continue submitting appraisals using the previous UAD 2.6 format through May 19, 2027.
This means some lenders will begin operating under the new requirements in November, while approved lenders may temporarily continue using the older format.
For buyers and Realtors, the practical takeaway is simple:
Don’t be surprised if appraisal reports look different from one transaction to another during the transition.
The applicable reporting format will depend on the lender’s implementation status and the specific appraisal submission.
3. More Detailed Reporting of Property Condition and Improvements
One of the biggest changes involves how appraisers document the physical characteristics and condition of a property.
The new URAR allows more detailed, structured reporting of interior and exterior conditions, improvements, deficiencies and other property features.
For example, the report can distinguish between the condition of a home’s interior and exterior when those conditions differ significantly.
It also provides a more organized way to identify defects, damage and deferred maintenance.
Why this matters to sellers
If you’ve completed significant improvements, it can be helpful to have accurate information available about the work.
That might include the age of major systems, dates of remodeling, building permits, additions and other significant improvements.
This information doesn’t guarantee a higher appraisal value, but it can help the appraiser understand the property’s characteristics.
Why this matters to buyers
The appraisal report may provide more detailed information about the property being purchased.
However, buyers should remember that an appraisal is not a substitute for a professional home inspection.
An appraiser’s primary responsibility is to develop an opinion of value and report information relevant to the lender’s collateral requirements.
4. Accessory Dwelling Units and Unusual Property Features
Accessory dwelling units have become increasingly relevant in residential real estate, particularly in markets where buyers are looking for multigenerational living arrangements or additional housing flexibility.
UAD 3.6 provides more structured reporting for ADUs, including characteristics such as their location, size, rooms and condition.
This is particularly relevant when a property includes:
- A detached backyard cottage
- An attached accessory dwelling unit
- A converted garage
- An additional living space with independent facilities
- Other unusual residential configurations
The new reporting structure does not automatically make every ADU eligible for financing.
Lenders must still evaluate the property under the applicable loan program requirements.
For Realtors: Accurate listing information about ADUs, permits, zoning and property configuration can help avoid confusion during appraisal and underwriting.
5. New Attention to Highest and Best Use
Another important development is Fannie Mae’s September 2026 clarification of its highest-and-best-use requirements for UAD 3.6 appraisals. Under the updated reporting requirements, the appraiser evaluates the property’s highest and best use as improved, rather than automatically analyzing the site as though it were vacant.
Highest and best use is an appraisal concept used to determine the most reasonably probable use of a property that is:
- Legally permissible
- Physically possible
- Financially feasible
- Maximally productive
Under the updated guidance, appraisers must report their analysis of these four considerations more explicitly.
Why does this matter?
Consider a property with an older single-family home located on land that could potentially support additional residential development.
The property’s current use and its highest and best use may not be the same.
The appraiser must evaluate the relevant property characteristics, legal restrictions and market conditions rather than assuming that the existing use necessarily represents the highest value.
Importantly, Fannie Mae’s updated guidance allows certain properties to remain eligible even when their current use is not their highest and best use, provided applicable residential-use and other eligibility requirements are satisfied.
This is not a blanket approval for every unusual property.
What Realtors should understand
Properties with redevelopment potential, multiple dwelling units, mixed residential and commercial uses, or unusual zoning may require additional analysis.
Accurate information about zoning, existing improvements, permitted uses and property characteristics can be especially helpful.
The changes also reinforce the importance of selecting comparable properties with similar highest-and-best-use characteristics when appropriate.
6. Hybrid Appraisals: A Different Way to Complete the Appraisal Process
While UAD 3.6 modernizes appraisal reporting, another development is changing how certain appraisals are performed.
It’s called a hybrid appraisal.
In a traditional appraisal, the appraiser generally performs the property inspection and develops the opinion of value.
A hybrid appraisal separates those responsibilities.
A trained and vetted property data collector visits the property to document its characteristics, condition, photographs and other required information.
A licensed or certified appraiser then reviews that information, performs the necessary market analysis and develops an independent opinion of value.
The appraiser remains responsible for the valuation.
Why are hybrid appraisals gaining attention?
Hybrid appraisals may offer several advantages:
- More efficient use of appraisers’ time
- Potentially faster appraisal turnaround times
- Standardized property data collection
- Greater flexibility in managing appraisal workloads
- More time for appraisers to focus on valuation analysis
These are potential benefits, not guarantees that every hybrid appraisal will be faster or less expensive.
Will every property qualify?
No.
Fannie Mae uses Desktop Underwriter to identify transactions eligible for hybrid appraisals.
Certain property types and loan scenarios are excluded. For example, Fannie Mae’s hybrid appraisal eligibility does not currently include 2- to 4-unit properties, manufactured homes or manually underwritten loans.
Hybrid appraisals are an option for eligible transactions, not a universal requirement created by UAD 3.6.
What Realtors should know
In an eligible hybrid appraisal, the person visiting the property may not be the appraiser developing the final opinion of value.
Instead, a property data collector gathers the required information for the appraiser’s review.
Realtors should understand who will be visiting the property and help facilitate access and the availability of accurate property information.
7. Desktop Appraisals and Value Acceptance: Not Every Transaction Follows the Same Path
Hybrid appraisals aren’t the only alternative to traditional appraisal procedures.
Depending on the lender, loan program and transaction, other valuation options may be available.
Traditional appraisal: An appraiser generally inspects the property and develops the opinion of value.
Desktop appraisal: An appraiser develops an opinion of value using available property information and other permitted data sources without personally conducting a physical property inspection.
Hybrid appraisal: A trained property data collector completes the property visit, and an appraiser develops the valuation.
Value acceptance: For eligible transactions, Fannie Mae may offer a valuation option under which the lender can proceed without obtaining an appraisal, subject to applicable requirements.
There is also value acceptance + property data, which involves collecting standardized property information without requiring a traditional appraisal when the transaction meets the applicable criteria.

These options are not interchangeable, and borrowers generally cannot simply choose whichever approach they prefer.
The lender must follow the applicable eligibility and underwriting requirements.
For buyers, this means the appraisal process may differ depending on the property, loan program, and underwriting findings. Appraisal requirements can also vary between conventional, FHA, VA, and jumbo financing. Learn more about these options on our Loan Programs page.
8. How Will These Changes Affect Homebuyers?
For most buyers, the mortgage process will remain familiar.
When an appraisal is required, the lender arranges for the appropriate appraisal process, and the resulting information is reviewed as part of underwriting.
However, buyers may encounter:
- A different-looking appraisal report
- More detailed reporting of property condition and improvements
- Different terminology for finished areas
- More structured information about ADUs
- A hybrid or desktop appraisal when eligible
- A value-acceptance option on qualifying transactions
- Questions or documentation requests involving unusual property characteristics
Will appraisal costs increase?
There is no universal answer.
Appraisal fees depend on several factors, including the property, location, complexity, assignment and appraisal provider.
UAD 3.6 does not establish a new nationwide appraisal fee.
Likewise, while alternative appraisal processes may improve efficiency, that does not guarantee lower costs for every borrower.
Could closings be delayed?
Any major industry transition creates the possibility of operational challenges.
Lenders, appraisal management companies, appraisers and technology providers are adapting their systems and workflows.
The temporary policy exception announced in September is intended to give qualifying lenders additional implementation time.
The best approach is to communicate early about appraisal requirements and any property characteristics that may need special attention.
9. What Sellers Should Do Before an Appraisal
Sellers don’t need to become appraisal experts, but preparation can be helpful.
Before the appraisal, consider gathering accurate information about:
- Major renovations and improvements
- Additions and changes to the property’s layout
- Permits and other relevant documentation
- ADUs and their configuration
- Finished areas and square footage
- Significant repairs or improvements
- Unusual property features
This information should be factual and available for the appraiser’s independent consideration.
Providing information is different from attempting to influence an appraiser’s value conclusion.

10. Five Things Realtors Should Do Now
For real estate professionals, the biggest opportunity is understanding how the new reporting structure and valuation options may affect transactions.
1. Become familiar with the URAR
The new appraisal report will look different from the traditional forms Realtors have seen for years.
Understanding its basic organization will make it easier to answer client questions.
2. Review listing information carefully
Accurate square footage, property configuration, ADU information and descriptions of improvements are important.
Avoid assumptions about finished areas or permitted uses that have not been verified.
3. Prepare for different property-visit procedures
Some eligible transactions may use hybrid appraisals or property data collection rather than a traditional appraisal inspection.
Knowing who is visiting the property and why can help prevent confusion.
4. Pay attention to unusual properties
Properties with ADUs, mixed uses, redevelopment potential, significant additions or condition issues may require additional analysis.
Consider discussing potential financing questions with the buyer’s lender early in the transaction.
5. Communicate with the lender
During the transition, lenders may be operating under different appraisal reporting formats.
Early communication can help identify issues involving property eligibility, appraisal ordering and required documentation.
11. What These Changes Mean for Mortgage Lenders
For mortgage professionals, the transition goes far beyond learning a new appraisal form.
Lenders and their partners must be able to order, receive, review and submit appraisal reports using the new data standard.
That can involve changes to:
- Loan origination and appraisal management systems
- Appraisal ordering procedures
- Underwriting and collateral review workflows
- Data validation and quality-control processes
- Appraiser and vendor coordination
- Pipeline management during the transition
Hybrid appraisals and standardized property data collection also introduce different operational processes.
The goal is to make property valuation information more consistent and useful while allowing appraisers to focus on their professional analysis.
But adopting new technology does not eliminate the lender’s responsibility to evaluate collateral and comply with applicable underwriting requirements.
12. What About FHA, VA and Other Loan Programs?
Not every mortgage program follows the same appraisal transition schedule or eligibility requirements.
FHA: The Federal Housing Administration has opened an optional production period for UAD 3.6 submissions. FHA-approved mortgagees may begin using the new format, while legacy submissions remain permitted during the transition. FHA has not yet established a mandatory adoption date.
VA: VA appraisal requirements and valuation processes remain subject to VA’s own program guidance. The Fannie Mae and Freddie Mac November 2 deadline should not be assumed to apply automatically to VA loans.
Other loan programs: Jumbo, portfolio and other non-agency lending programs may have their own appraisal requirements and adoption schedules.
The important point is that appraisal requirements depend on the specific loan program and lender, not simply the type of property being purchased.
13. Will These Changes Make Buying or Selling a Home More Difficult?
Not necessarily.
The purpose of these changes is to modernize how property information is documented and evaluated.
Better structured information may help improve consistency, identify potential issues and support more efficient appraisal reviews.
At the same time, the transition will require training, technology updates and coordination among industry participants.
For buyers and sellers, the fundamental process remains largely the same.
A property’s market value still depends on relevant market evidence, property characteristics and professional appraisal analysis when an appraisal is required.
The Bottom Line: Preparation Matters More Than Ever
The changes arriving in 2026 represent a significant modernization of the residential appraisal industry.
UAD 3.6 introduces a new reporting structure, while hybrid appraisals, desktop appraisals and value-acceptance options provide different approaches for eligible transactions.
Updated highest-and-best-use guidance and more detailed property reporting also reinforce the importance of accurate information about the home.
For Realtors, understanding these changes can help prevent confusion, improve communication and better prepare clients.
For buyers and sellers, working with professionals who understand appraisal requirements can help make the financing process more predictable.
And for mortgage lenders, the transition represents an opportunity to improve processes while maintaining appropriate valuation and underwriting standards.
Have Questions About an Upcoming Purchase?
Whether you’re purchasing your first home, moving into your next home or representing a buyer or seller, understanding the financing and appraisal process is an important part of a successful transaction.
I work with buyers and real estate professionals throughout Whatcom County, Snohomish County and surrounding Washington communities.
If you have questions about an unusual property, appraisal requirements or financing options, I’d be happy to talk through the details.
Jay Richardson
Mortgage Loan Originator | Edge Home Finance LLC
This article provides general educational information. Appraisal eligibility, valuation options and underwriting requirements vary by loan program, lender and transaction. Program requirements are subject to change.
Leave a Reply